What New Financial Standards Must Stablecoin Issuers Meet in 2027?

The GENIUS Act is set to reshape the U.S. stablecoin market when its regulatory framework takes effect on January 18, 2027. The legislation introduces stricter requirements for stablecoin reserves, redemptions, capital and issuer supervision, while creating new opportunities for banks to enter the digital-dollar business. For crypto companies, the transition could bring higher compliance costs and tighter rules on stablecoin distribution.
With the Office of the Comptroller of the Currency (OCC) already finalizing key implementation requirements, attention is shifting to how these changes will affect competition, institutional adoption and the future of digital payments.
This report examines what the GENIUS Act changes in 2027, what banks and stablecoin issuers must prepare for, and how the new rules could reshape the U.S. crypto market.
GENIUS Act Establishes a Federal Framework for Stablecoins
The Guiding and Establishing National Innovation for U.S. Stablecoins Act, known as the GENIUS Act, was signed into law on July 18, 2025. It establishes a federal framework for payment stablecoins, defining who can issue them and the regulatory standards they must meet.
Under the law, payment stablecoins can generally be issued only by permitted payment stablecoin issuers. These include eligible subsidiaries of insured depository institutions, federally qualified nonbank issuers and qualifying state-regulated issuers.
The framework also divides regulatory responsibilities among federal and state authorities. The OCC will supervise issuers under its jurisdiction, while other regulators, including the Federal Reserve and FDIC, will oversee entities within their respective mandates.
On October 21, 2026, the OCC finalized its implementation rule for issuers under its supervision. The rule covers reserve assets, redemption, capital, risk management, custody, reporting and licensing. However, anti-money laundering and sanctions requirements remain subject to separate rulemaking.
GENIUS Act: Key Dates to Watch
Stablecoin Issuers Face Stricter Reserve and Redemption Requirements
Reserve backing is one of the most important parts of the GENIUS Act. Issuers must maintain eligible reserve assets worth at least 100% of their outstanding payment stablecoins. Permitted assets include U.S. currency, qualifying bank deposits, short-term Treasury securities, certain repurchase agreements and government money market funds.
The requirement is designed to ensure that issuers can meet customer redemption requests without relying on uncertain or illiquid assets. Issuers must also publish monthly disclosures detailing their reserve composition and establish clear redemption policies.
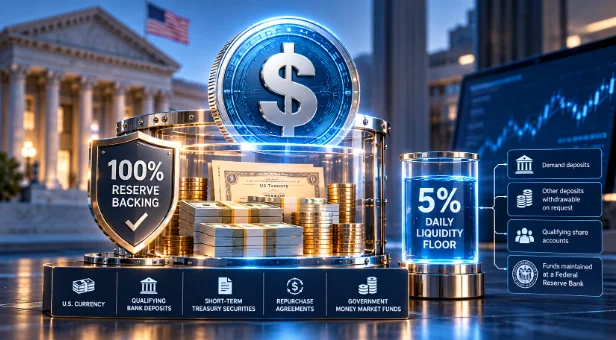
The OCC’s final rule adds liquidity and risk-management standards for issuers under its jurisdiction. It includes a 5% daily-liquidity floor and requires reserve stress testing and the ability to demonstrate that assets can be monetized reliably under adverse conditions.
The legislation also prohibits permitted payment stablecoin issuers from paying interest or yield to holders solely for holding, using or retaining their stablecoins. This could affect how issuers and distribution partners structure rewards programs, particularly those that resemble interest payments on digital-dollar balances.
Banks Could Gain a Larger Role in the Stablecoin Economy
The GENIUS Act creates a formal route for eligible banking institutions to participate in stablecoin issuance through approved subsidiaries. This could allow banks to expand beyond traditional deposits and payment services into regulated digital-dollar infrastructure.
Potential opportunities include issuing payment stablecoins, holding reserve assets, providing digital asset custody and supporting institutional payment services. Banks already have established relationships with regulators and experience managing liquidity, which could become important advantages in a market where reserve quality and redemption reliability are central.
However, participation will require regulatory approval and compliance with capital, operational and risk-management standards. The FDIC has also proposed requirements for institutions under its supervision, including rules covering stablecoin-related custody and safekeeping activities. Those proposals should not be confused with the OCC’s finalized October framework.
The competitive question is whether banks can use their existing infrastructure to become major stablecoin providers or whether crypto-native companies will retain an advantage in blockchain integration and global distribution.
Capital and Compliance Requirements Could Reshape the Issuer Market
The GENIUS Act introduces prudential standards intended to ensure that stablecoin issuers can withstand financial, operational and liquidity pressures. These requirements could increase the cost of operating, particularly for smaller companies without established compliance teams or institutional banking relationships.
Under the OCC’s final rule, issuers within its jurisdiction must meet a capital framework based on GAAP equity, subject to specified deductions. The rule also establishes an ongoing $5 million minimum capital floor. Capital and operational backstop requirements must be maintained at all times, rather than assessed only at quarter-end.
These requirements could put smaller issuers under pressure to raise additional capital, strengthen their compliance infrastructure or partner with regulated financial institutions. Larger companies may be better positioned to absorb the costs, potentially increasing the importance of scale in the stablecoin market.
Crypto Exchanges Face New Rules for Stablecoin Distribution
The impact of the GENIUS Act extends beyond stablecoin issuers. Crypto exchanges and other digital asset service providers will also need to review which payment stablecoins they offer to U.S. customers. From July 18, 2028, digital asset service providers generally cannot offer or sell payment stablecoins to people in the United States unless those stablecoins are issued by permitted payment stablecoin issuers or qualify under the law’s foreign-issuer provisions.
Foreign-issued stablecoins face a separate requirement from January 18, 2027. Digital asset service providers cannot make these stablecoins available in the United States unless the foreign issuer has the technological capability to comply with lawful U.S. orders and meets the applicable statutory conditions.
Will the GENIUS Act Accelerate Institutional Stablecoin Adoption?
Regulatory clarity could make payment stablecoins more attractive to banks, payment companies and businesses seeking alternatives to traditional settlement systems. Stablecoins can move across blockchain networks and support transfers outside conventional banking hours, creating potential benefits for cross-border payments and liquidity management.
The GENIUS Act addresses a major barrier to institutional participation by defining who can issue payment stablecoins and what standards those issuers must meet. However, regulatory approval alone will not guarantee adoption.
Financial institutions will continue to assess redemption reliability, custody arrangements, transaction costs, blockchain interoperability and counterparty exposure. Another important consideration is that payment stablecoins are not automatically bank deposits and do not carry the same deposit-insurance protection for holders. The FDIC has proposed that deposits held as reserves backing stablecoins would not receive pass-through deposit insurance for stablecoin holders.
The next phase will depend on whether regulated issuers can turn compliance into reliable payment products that businesses and financial institutions are willing to use at scale.
What Still Needs to Be Resolved Before the 2027 Rollout?
Although the OCC has finalized a major part of its implementation framework, several regulatory processes remain separate. Anti-money laundering, customer identification and sanctions requirements are being addressed through additional rulemaking involving the Treasury Department and other federal agencies.
The FDIC has also issued proposals covering capital, reserve management, redemption and custody for issuers under its supervision. Meanwhile, the Treasury Department has proposed rules addressing the issuance, offer and sale of payment stablecoins in the United States, including the treatment of foreign issuers.
These outstanding measures matter because banks and crypto companies will need to comply with requirements from the regulator responsible for their activities. The final details could influence licensing timelines, operational costs and the ability of foreign stablecoin providers to serve U.S. customers.
Key Regulatory Questions for 2027
What Happens Next?
The GENIUS Act takes effect on January 18, 2027, introducing a new regulatory framework for U.S. payment stablecoins. Banks, issuers and crypto platforms will need to adapt to its requirements as regulators complete the remaining implementation rules.